Making Insurance Simple, One Insight at a Time.
Can I Insure a Car Not in My Name? Avoid These 2026 Mistakes
Wondering can I insure a car not in my name? Learn how insurable interest, non-owner policies, and state rules affect your options before you drive or insure a car you do not own.
Quick Summary
If you’re wondering can I insure a car not in my name, the short answer is that it is sometimes possible, but it is usually difficult. Insurers want you to have an insurable interest, meaning you would suffer a direct financial loss if the vehicle were damaged, so they often decline standard policies when you are not the registered owner. Your realistic options are to be listed as a driver on the owner’s policy, to buy a non-owner car insurance policy if you do not have regular access to a car, or to share a title or household with the owner.
Table of Contents
Table of Contents
- Understanding Insurable Interest: Can I Insure a Car Not in My Name?
- Practical Steps: How to Insure a Car That Is Not in My Name
- Alternative Policy Options: Can I Insure a Car Not in My Name?
- DMV Registration Rules: Can I Insure a Car Not in My Name?
- State Guidelines: Can I Insure a Car Not in My Name in NY, TX, or CA?
- Comparing Big Carriers: Can I Insure a Car Not in My Name with Progressive or GEICO?
- Frequently Asked Questions
- Conclusion
1. Understanding Insurable Interest: Can I Insure a Car Not in My Name?
The legal idea behind this question is insurable interest. Insurance exists to protect people from financial loss, so a standard insurer will hesitate when you would not lose money if the car were damaged. That is why the question of whether you can insure something that is not yours usually comes back to ownership.
Without ownership, a driver has no clear financial stake in the car itself. That creates a hurdle if you want to insure a car that is not in your name. After a covered loss, the payment for vehicle damage typically goes to the owner or lienholder, not to the person paying the premium. Underwriters look closely at the relationship between the owner and the policyholder for that reason, and to prevent fraud.
2. Practical Steps: How to Insure a Car That Is Not in My Name
If you regularly drive a vehicle owned by someone else, there are a few practical methods to ensure the vehicle is legally covered without running into underwriting issues:
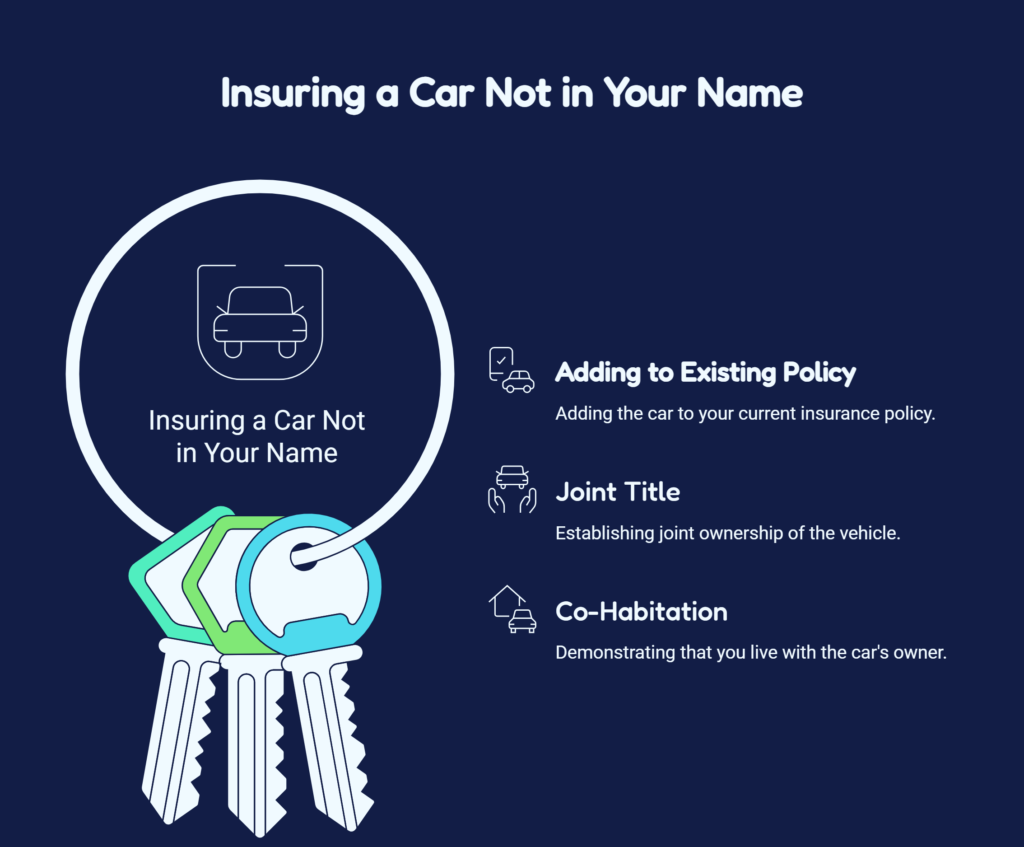
Adding a Car to an Existing Insurance Policy:
The easiest approach is for the vehicle owner to add you to their current auto policy as a listed driver. Alternatively, if you live in the same household, you may be able to add their car to your policy, provided the insurer permits multi-car policies with split ownership among household members.
Establishing a Joint Title:
If you want a smoother insurance process, you can work with the owner to update the title at your local DMV to include both names. Once your name is on the title, you generally have an insurable interest and can buy your own policy. Retitling can involve fees or taxes in some states, so check with your DMV first.
Demonstrating Co-Habitation:
Many insurance companies will allow you to insure a car that isn’t in your name if you and the car owner live at the same physical address. This is common for couples, roommates, or family members sharing a single residence.
To see how one auto insurance provider handles coverage, costs, and claims, read our Amtex Auto Insurance Guide: Coverage, Cost & Claims.
3. Alternative Policy Options: Can I Insure a Car Not in My Name?
When a traditional policy is not a viable option, consumers turn to alternative coverage products tailored for non-owners:
Non-Owner Car Insurance Explained:
A non-owner car insurance policy is designed for people who do not own a vehicle but drive borrowed or rented cars. It typically provides liability coverage that applies after the car owner’s policy pays first, which helps if a claim exceeds the owner’s limits. It does not cover damage to the car you are driving. Insurers generally do not write these policies for people who have regular access to a household vehicle, because the owner’s policy is expected to cover that driver.
Temporary Car Insurance for Borrowed Vehicles:
For a short-term need, ask the owner’s insurer whether occasional drivers are covered under permissive use, which depends on the policy and the state. Policies lasting only a few days are uncommon, so check availability with the insurer before you count on one.
Insuring a Leased or Financed Vehicle:
If the vehicle is leased or financed, the lender or leasing company holds an interest in it and sets the insurance requirements. Lenders typically require comprehensive and collision coverage, and leasing companies often require gap coverage and higher liability limits. Because those requirements attach to the car, they are normally met through the owner’s policy.
4. DMV Registration Rules: Can I Insure a Car Not in My Name?
People often ask: can I register a vehicle if the insurance is not in my name? Registration and insurance are handled by different agencies, and the rules vary. States generally require proof that a vehicle is insured before it can be registered, and many insurers want the policy to list the registered owner. New York is stricter and generally requires the policy to match the registered owner. If the names do not line up, the insurer or the DMV may ask for more information or refuse the filing.
Does a vehicle have to be registered in the owner’s name? In general, yes. A vehicle is registered to the person or people named on its title, so someone else can register it only through a joint registration or a legal transfer of ownership.
Your state DMV handles registration and titling, while your state insurance department regulates insurers and policies. If the two seem to conflict, ask both, and ask a licensed agent how your insurer handles ownership.
5. State Guidelines: Can I Insure a Car Not in My Name in NY, TX, or CA?
Auto insurance is regulated state by state, so your options depend on where the car is registered and garaged. The notes below are general, and you should confirm the details with your state DMV and a licensed agent.
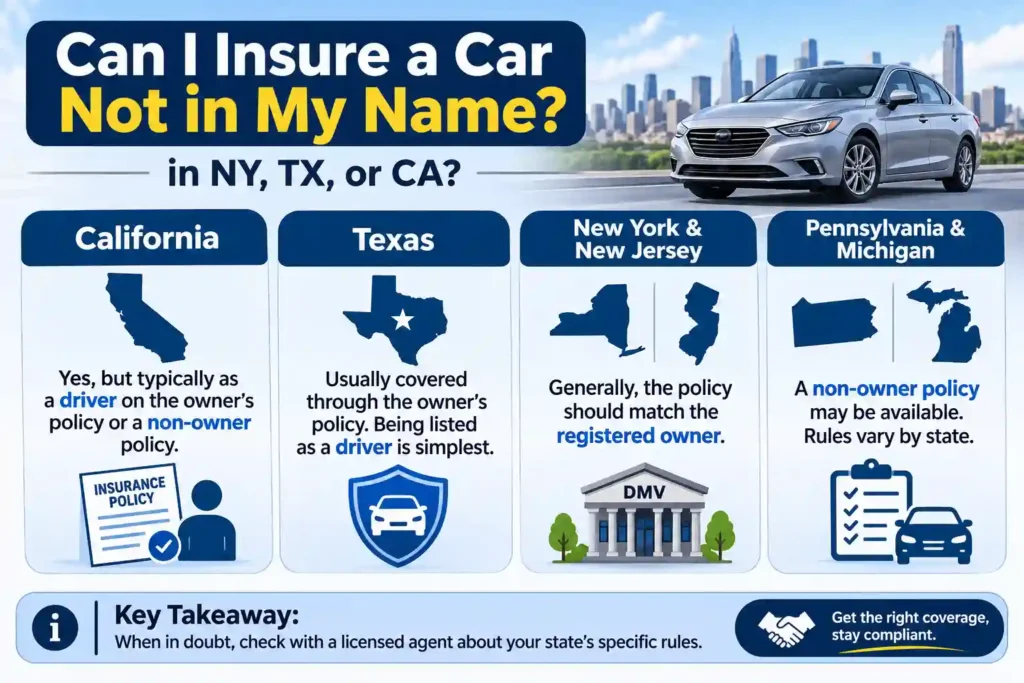
California:
Can I insure a car not in my name in California? California requires a vehicle to be insured to be registered and driven. If you drive a car that belongs to someone else, the usual routes are being listed as a driver on the owner’s policy or buying a non-owner policy, since most insurers want the registered owner on the policy for the car itself.
Texas:
Can I insure a car not in my name in Texas? Texas uses TexasSure, an automated database run by state agencies to identify vehicle owners without required insurance. A car in someone else’s name is normally kept in compliance through the owner’s policy, so being listed as a driver on it is the simplest route.
New York and New Jersey:
Can I insure a car not in my name in NY or NJ? New York tracks insurance on registered vehicles through the DMV’s Insurance Information and Enforcement System, and the policy generally needs to match the registered owner. In New Jersey, confirm the requirements with the state Motor Vehicle Commission and your insurer before you buy a policy for a car you do not own.
Pennsylvania and Michigan:
Can I insure a car not in my name in PA or Michigan? Whether a non-owner policy is available, and how it works with each state’s coverage rules, varies by insurer. Michigan’s no-fault system and Pennsylvania’s choice between limited and full tort both affect injury coverage, so ask a licensed agent how a policy would apply to you.
North Carolina:
Can I insure a car not in my name in NC? North Carolina sets its registration and insurance rules through the state DMV and Department of Insurance, so confirm the details with them and a licensed agent. In general, a car you drive regularly should be covered by a policy that lists you or the owner, not by a non-owner policy.
6. Comparing Big Carriers: Can I Insure a Car Not in My Name with Progressive or GEICO?
Each insurer sets its own underwriting rules on vehicle ownership, and those rules change, so the answer to can I insure a car not in my name varies widely by company and state. The notes below are general, so confirm the details with the insurer.
Progressive Guidelines
Can I insure a car not in my name with Progressive? Progressive offers non-owner policies, which cover liability only and do not include collision or comprehensive. To insure a specific car that someone else owns, Progressive, like most insurers, will look for an insurable interest and usually a connection to the owner such as a shared household. Ask Progressive directly about your situation.
GEICO Guidelines
Can I insure a car not in my name with GEICO? GEICO also offers non-owner policies for people who regularly drive borrowed or rented cars. For a specific car that is not in your name, GEICO generally looks for an insurable interest, which can be hard to show unless you depend on the car, so ask an agent about your situation. New York is stricter, with the registration and insurance names generally required to match.
7. Frequently Asked Questions
Can someone else insure my car if the title is under my name?
Yes, someone else can insure your car if the title is under your name, but most insurance companies will require that person to live in your household or be added to a joint policy where your insurable interest as the owner is formally acknowledged.
Can you insure a car that is not registered in your name?
Generally, you cannot insure a car that is not registered in your name on a standalone policy. Most insurance companies and state DMVs require the names on the vehicle registration and the auto insurance policy to match exactly.
Can you be on someone else’s car insurance if you don’t live with them?
Typically, you cannot be added to someone else’s car insurance if you do not live with them. Auto insurers calculate risk based on where the vehicle is parked overnight. However, exceptions exist for students away at college or family members under specific co-ownership agreements.
Can you be on someone else’s car insurance in another state?
Being on a policy in another state is highly restricted. Insurance policies must be rated for the specific state where the car is garaged. If you drive the vehicle in a different state long term, it must have a policy compliant with that specific state’s laws.
Can you insure a car that is not registered yet?
Yes. This is common when you buy a vehicle. Insurers will let you buy a policy using the Vehicle Identification Number (VIN) so that you have proof of insurance, which is required before you can legally register the vehicle at the DMV.
Can I insure my son if he doesn’t live with me?
If you are asking can i insure my son if he doesn’t live with me, the answer depends on car ownership. If the car title is in your name, you can maintain the insurance policy, but you must inform the insurer where the car is garaged. If the car title is in your son’s name and he lives away from home, he will generally need his own independent policy.
Can I put my girlfriend’s car on my insurance?
You can usually add your girlfriend’s car to your policy only if you live together and share a household address. If you live separately, she should keep her own policy, or you can be listed as a driver on hers.
Can I insure a car without a license?
Some insurers will write a policy for an owner who does not hold a valid license, but you cannot be listed as an active driver. You would need to name a licensed person as the primary operator, and availability varies by company and state.
What if the car is insured but not the driver?
If an unlisted driver operates the insured vehicle with the owner’s permission, the insurance coverage usually extends to them under permissive use guidelines. However, if the driver resides in the household and is not explicitly listed on the policy, the claim could be denied under common policy exclusions.
Can I drive a car if I am not the owner?
Yes, you can drive a car you do not own as long as you have the owner’s explicit permission and the vehicle has active, valid insurance that covers permissive drivers. In most cases the owner’s policy is the first to pay if something goes wrong.
Ownership rules are just one piece of how auto insurance works. For the bigger picture, including coverage types and ways to lower what you pay, see Auto Insurance Guide (2026): How to Lower Your Premiums.
8. Conclusion
The short answer to can I insure a car not in my name is that it is possible in some situations, but insurable interest makes it hard. Most drivers end up with one of three solutions: being added to the vehicle owner’s policy, buying a non-owner policy when they have no regular access to a car, or sharing the title at the DMV. Because insurers and states enforce different rules for titles, registrations, and insurance cards, contact a licensed agent or use the state directory from the National Association of Insurance Commissioners to confirm the rules before you drive or insure a car you do not own.
Disclaimer: This article is for general educational purposes only and is not legal or insurance advice. Insurer rules and state laws change, so confirm the details with a licensed agent, your state DMV, or your state insurance department.