Making Insurance Simple, One Insight at a Time.
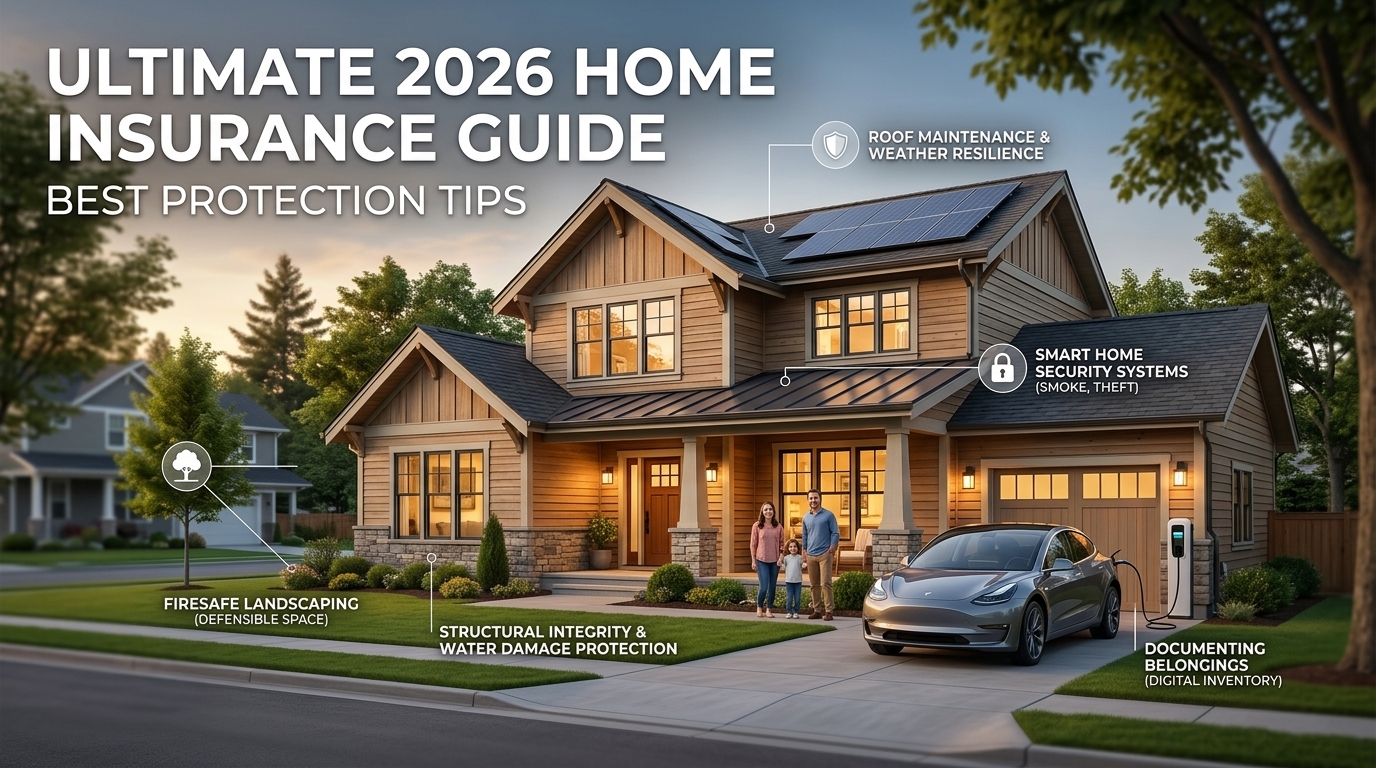
Ultimate 2026 Home Insurance Guide: Best Protection Tips
Secure your property with this ultimate home insurance guide. Learn the best coverage tips and proven ways to lower your premiums today!
Quick Summary
Navigating residential property protection in the United States requires a clear understanding of coverage structures, pricing mechanisms, and claim procedures. This home insurance guide breaks down the essentials of securing residential property across all ownership types. Homeowners policies protect physical structures, personal belongings, and legal liabilities against unexpected catastrophes like fires or severe weather.
Renters policies focus strictly on personal possessions and liability without charging for structural repairs. Premiums depend on regional risk factors, rebuilding expenses, deductible choices, and individual property characteristics. Understanding policy terms, maintaining digital property inventories, and knowing how to navigate claims helps you get a fairer payout when disaster strikes.
Table of Contents
Table of Contents
1. Understanding Home Insurance Basics
What is Home Insurance?
What is home insurance in practical terms? It is a legal contract between a property occupant and an insurance carrier where the carrier agrees to cover specified financial losses caused by accidental perils in exchange for regular premium payments. This contract creates a financial safety net that prevents homeowners from facing ruinous out-of-pocket costs if their dwelling suffers structural destruction or severe weather damage.
How Does Homeowners Insurance Work?
Understanding how does homeowners insurance work involves looking at the relationship between financial risk transfer and policy guidelines. When you purchase a policy, you select specific coverage limits and an out-of-pocket deductible. If a fire, storm, or vandal damages your home, you file a claim with your carrier. After you pay your designated deductible, the insurer reimburses the remaining covered costs up to your policy limit.
When buying a home with a mortgage, lenders require an active homeowners policy prior to closing. The lender usually sets up an escrow account to hold a portion of your monthly mortgage payment specifically for property taxes and home insurance premiums, ensuring the collateral protecting their loan remains insured.
Renters Insurance vs Homeowners Insurance
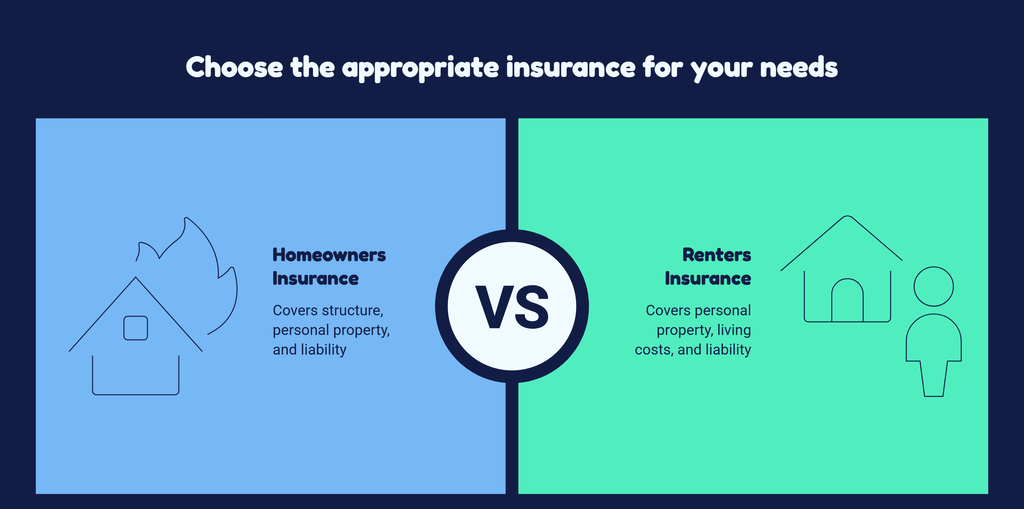
Analyzing renters insurance vs homeowners insurance highlights key structural differences based on property ownership. Homeowners insurance covers the physical exterior and interior structure of a building along with personal belongings and personal liability. Renters insurance excludes structural building coverage entirely because the landlord owns the physical building. Instead, renters coverage concentrates solely on protecting personal property inside the unit, temporary living costs during covered repairs, and personal liability protection.
2. Breaking Down Coverage Types
Homeowners Insurance Coverage
Standard homeowners insurance coverage is organized into core categories within a standard policy, usually designated as an HO-3 policy form:
- Dwelling Coverage (Coverage A): Reimburses repairs or total rebuilding costs for the primary home structure, including roofs, foundation, walls, and attached garages.
- Other Structures (Coverage B): Protects standalone property elements like detached garages, tool sheds, fences, and guest houses.
- Personal Property (Coverage C): Pays to replace furniture, electronics, clothing, and appliances damaged by covered hazards.
- Loss of Use / Additional Living Expenses (Coverage D): Pays for temporary housing, hotel bills, and restaurant dining if a covered loss renders your house unlivable during repairs.
According to the Insurance Information Institute, about 5.3 percent of insured homes had a claim in 2023, roughly one claim for every 18 insured homes.
Renters Insurance Coverage
Comprehensive renters insurance coverage provides financial safety for tenants without forcing them to pay for building repairs. A typical HO-4 policy includes contents protection for electronics, clothes, and furniture against theft, fire, smoke, and water burst incidents. It also includes loss of use benefits to cover living expenses if an apartment becomes uninhabitable after a covered event.
Property Damage Coverage
In any property contract, property damage coverage explicitly pays to repair or replace physical assets damaged by named perils such as lightning, windstorms, hail, or vandalism. It does not pay for routine wear and tear or gradual maintenance issues. Many policies include an 80 percent rule. This rule dictates that you must carry dwelling coverage equal to at least 80 percent of your home’s total replacement cost value to receive full reimbursement on partial losses without incurring penalty deductions.
Liability Protection
Personal liability protection shields your personal savings if a visitor suffers bodily injury on your premises or if you accidentally damage someone else’s property. For example, if a guest slips on your icy driveway or your dog bites a passerby, liability coverage pays for legal defense expenses, medical bills, and court settlements up to your designated limit.
3. Home Insurance Cost Factors & Rates
Home Insurance Cost Overview
The total home insurance cost for a residential property varies significantly based on structural value, regional weather trends, and policy design. The Insurance Information Institute, using NAIC data, puts the national average homeowners premium at about $1,569 a year for 2022. Your price depends on your state, your home’s rebuilding cost and your deductible, and homes in high-risk weather areas usually pay more.
Renters Insurance Cost by State
Looking at renters insurance cost by state demonstrates how location changes pricing expectations. The Insurance Information Institute reports an average renters premium of about $171 a year for 2022. Prices are usually higher in areas with more hurricane, theft or wildfire risk. For example, tenants evaluating coastal or southern housing options can read our detailed guide on Renters Insurance Georgia (2026): Coverage, Costs & Savings Tips to learn how location impacts premium pricing. Similarly, tenants in Midwestern markets can review Renters Insurance Ohio (2026): Coverage, Costs & Savings Tips to explore location-specific pricing structures and discounts.
Regional risks differ. Coastal states face hurricanes, wind and flooding. Midwest states see severe hail and tornadoes. Western states face wildfires and earthquakes. Each of these affects what insurers charge.
Homeowners Insurance Rates & Pricing Calculations
Insurers determine homeowners insurance rates by assessing risk levels per $1,000 of insured value. To calculate your needed coverage, estimate the local labor and material costs required to rebuild your home from the ground up rather than relying on market resale prices. Multiplying your house square footage by local per-square-foot reconstruction costs gives an accurate starting point for dwelling coverage limits.
Factors That Affect Home Insurance Premiums
Understanding the key factors that affect home insurance premiums helps homeowners find meaningful savings. Insurers evaluate the following variables when underwriting a quote:
- Geographic Location: Proximity to coastlines, wildfire zones, or active fault lines increases overall risk.
- Home Age and Building Materials: Older electrical, plumbing, and roofing systems elevate claim likelihood.
- Deductible Level: Choosing a higher deductible lowers annual premiums, while a lower deductible increases regular billing costs.
- Claims History: A history of prior property claims leads to higher individual rates.
- Credit History: In most states, insurance-based credit scores directly influence rate calculations.
4. Choosing Insurance Providers & Special Property Situations
Best Homeowners Insurance Companies & Reviews
Identifying the best homeowners insurance companies requires evaluating financial stability, customer service track records, and speed of claim payouts. Utilizing home insurance company reviews published by independent rating firms like A.M. Best and J.D. Power gives unbiased insights into how reliably a carrier fulfills policy obligations during major regional disasters. To see how regional carriers perform against national insurers, check out our La Familia Insurance Review (2026): Coverage, Cost & Complaints for an in-depth breakdown of carrier options.
Renters Insurance Companies & Townhome Insurance Providers
Evaluating renters insurance companies and specialized townhome insurance providers involves checking digital management tools, custom endorsement options, and bundling discounts. Leading national carriers often allow policyholders to bundle tenant or townhome coverage directly with auto policies to earn multi-policy savings.
Townhome Insurance and Condo Insurance
Different property architectures require tailored insurance contracts:
- Townhome Insurance: Protects multi-level attached units. Depending on your HOA master contract, townhome insurance may cover the entire structure or focus solely on interior spaces. You can learn about specific policy terms in our article on Allstate Townhome Insurance: Best 2026 Coverage & Cost Guide.
- Condo Insurance: Known as an HO-6 policy, condo insurance covers internal walls, fixtures, cabinetry, personal property, and liability, relying on the condominium association master policy to cover exterior walls and shared common areas.
Property and Casualty Insurance Explained
Having property insurance explained clearly helps property owners distinguish between asset protection and legal protection. Under the broad category of property and casualty insurance, property insurance covers physical losses to your dwelling and belongings, while casualty insurance covers legal liability if your negligence causes personal injury or property damage to third parties. Readers interested in regional regulatory details and carrier mechanics can consult our Property and Casualty Insurance Hartford: The Complete 2026 Guide.
5. Managing Claims, Disputes, and Denials
How to File a Claim Step-by-Step
Knowing how to file a claim correctly speeds up reimbursement and prevents unnecessary delays. Follow these steps after suffering property damage:
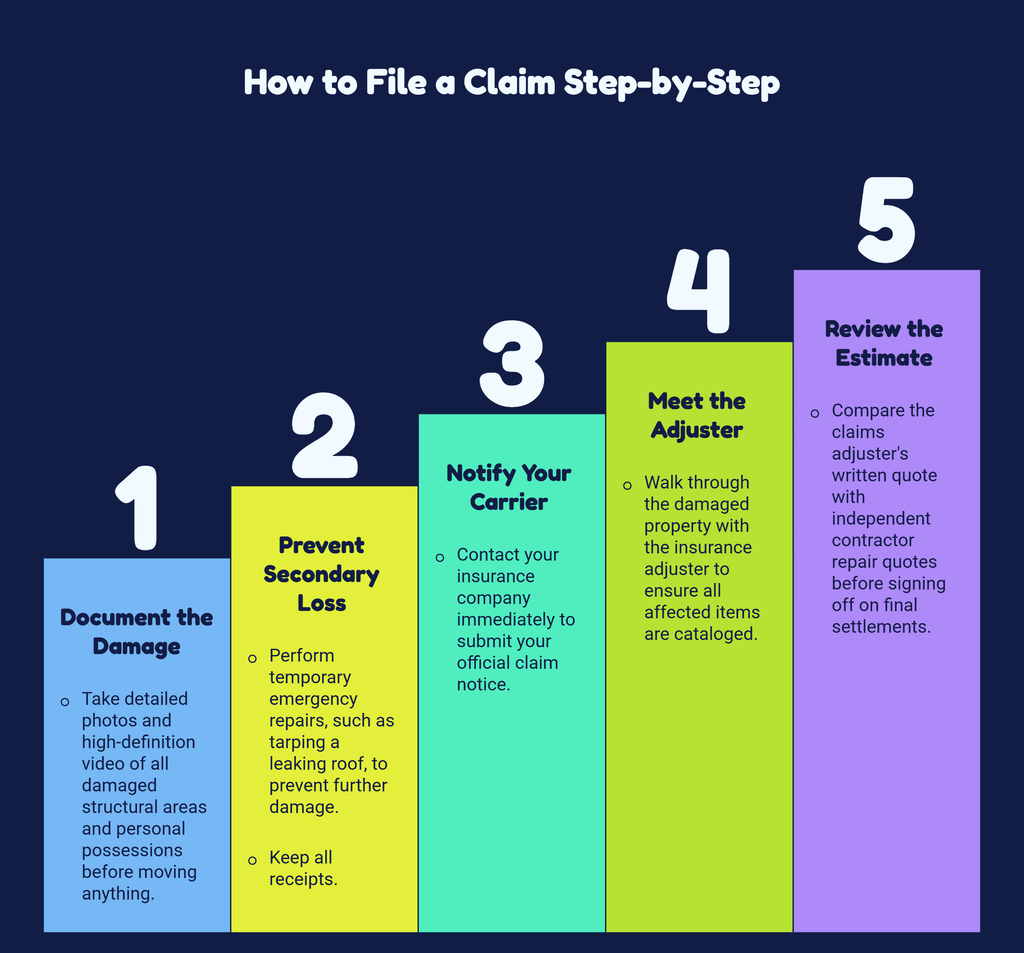
- Document the Damage: Take detailed photos and high-definition video of all damaged structural areas and personal possessions before moving anything.
- Prevent Secondary Loss: Perform temporary emergency repairs, such as tarping a leaking roof, to prevent further damage. Keep all receipts.
- Notify Your Carrier: Contact your insurance company immediately to submit your official claim notice.
- Meet the Adjuster: Walk through the damaged property with the insurance adjuster to ensure all affected items are cataloged.
- Review the Estimate: Compare the claims adjuster’s written quote with independent contractor repair quotes before signing off on final settlements.
Handling a Denied Home Insurance Claim
Receiving a denied home insurance claim notice can be alarming, but it is not always the final word. Claims are often rejected due to unbacked damage claims, missing documentation, or exclusions like flood and earthquake hazards. Review the denial letter thoroughly to see which specific policy language your carrier cited.
Resolving a Homeowners Insurance Dispute
If you run into a serious homeowners insurance dispute regarding low payout offers or improper claim rejections, you have rights. You can hire an independent public adjuster to evaluate structural damages, file an official appeal with your insurer’s dispute resolution department, or submit a formal complaint to your state Department of Insurance.
6. Frequently Asked Questions (FAQs)
What is the 80% rule in home insurance?
The 80% rule states that homeowners must carry dwelling coverage equal to at least 80% of their home’s full replacement value. If your coverage falls below 80%, the insurer will not pay the full replacement cost on partial damage claims, leaving you responsible for a proportional coinsurance penalty out of pocket.
How do I calculate my home insurance coverage needs?
Calculate dwelling coverage by multiplying your home’s total square footage by local building reconstruction costs per square foot. Personal property coverage is often set at about 50% of the dwelling limit by default, and you can usually raise it. Choose a personal liability limit that fits your assets.
What is not covered by standard home insurance?
Standard home insurance policies explicitly exclude damage caused by rising floodwaters, earthquakes, maintenance neglect, pest infestations, sewer backups, and normal wear and tear. Specialized endorsement riders or separate policies are required for flood and earthquake protection.
For a full comparison, see our Flood Insurance vs Homeowners Insurance: What Each Covers (2026).
How does homeowners insurance work when buying a house with a mortgage?
When purchasing a house with a mortgage, your lender requires proof of an active home insurance policy before releasing loan funds. The lender typically creates an escrow account where a portion of your monthly mortgage payment goes toward paying your annual home insurance bill automatically.
What is the difference between replacement cost and actual cash value?
Replacement cost coverage pays the full amount needed to buy new materials or items at current market prices without deducting for age or wear. Actual cash value subtracts depreciation from your payout, reimbursing only what the item was worth immediately before the loss occurred.
How much should home insurance cost on a $400,000 house?
There is no single price for a $400,000 house. The Insurance Information Institute, using NAIC data, puts the national average at about $1,569 a year for 2022 across all home values. Your cost depends on your state, weather risks, deductible and rebuilding costs, so compare quotes from several insurers.
Is $200 a month a lot for home insurance?
$200 a month is $2,400 a year, which is above the 2022 national average of about $1,569 reported by the Insurance Information Institute. Prices vary a lot by state and by the value of the home, so compare quotes from several insurers to see whether your rate is high for your area.
What are the main types of homeowners insurance coverage?
The three main foundational types of coverage inside a standard homeowners policy are Dwelling Coverage (protecting the structure), Personal Property Coverage (protecting belongings), and Personal Liability Protection (protecting against legal/medical lawsuits from injuries on the property).
What is the most common home insurance claim?
According to the Insurance Information Institute, wind and hail account for the largest share of homeowners losses (about 42.5% in 2023), followed by water damage and freezing (about 22.6%) and fire and lightning (about 21.6%).
What lowers your homeowners insurance premiums?
You can lower your premiums by raising your out-of-pocket deductible, bundling home and auto policies with the same carrier, installing monitored security systems, upgrading aging roofs or plumbing, and maintaining a high credit score.
Is it a bad idea not to have home insurance?
Yes. If you have a mortgage, skipping insurance violates your loan agreement and triggers expensive lender-placed coverage. Even if your home is fully paid off, going uninsured leaves your primary asset vulnerable to catastrophic financial loss from fires, storms, or lawsuits.
What should you not say to a home insurance adjuster?
Never admit fault, speculate about the cause of damage, declare that damage was pre-existing or caused by poor maintenance, or claim that repairs will be quick and easy before getting a professional contractor estimate. Stick strictly to facts and photo evidence.
How do you read a homeowners insurance quote?
When reading a quote, check the Declarations Page for four key details: the Dwelling Coverage limit (Coverage A), the deductible amount you pay out-of-pocket, the premium breakdown (annual vs. monthly), and any explicit policy exclusions or optional endorsement add-ons.
What is the difference between property and casualty insurance?
Property insurance protects physical structures and personal belongings against direct financial loss from damage or theft. Casualty insurance focuses on legal liability protection, paying damages if your negligence causes bodily injury or property damage to another party.
7. Conclusion
Securing the right residential policy boils down to understanding your property’s specific physical needs, evaluating local risk factors, and picking coverage limits that safeguard your total assets. Whether managing an HO-3 policy for a single-family house, navigating shared structures with townhome policies, or protecting personal possessions as a tenant, keeping a detailed home inventory and periodically auditing coverage limits prevents severe financial shortfalls.
By proactively comparing quotes, optimizing deductibles, and knowing how to navigate claims, property owners and renters across the United States can build a secure, cost-effective financial safety net for years to come.
Disclaimer:
The information provided in this ultimate home insurance guide is published strictly for educational and informational purposes. Our platform is an independent educational resource and does not directly offer, underwrite, sell, or solicit insurance products or policies. We are not an insurance broker or carrier. All information herein is tailored specifically to property structures, regulatory standards, and insurance practices within the United States. Readers should consult with a licensed insurance agent or financial professional to assess their specific personal property requirements.